The Situation
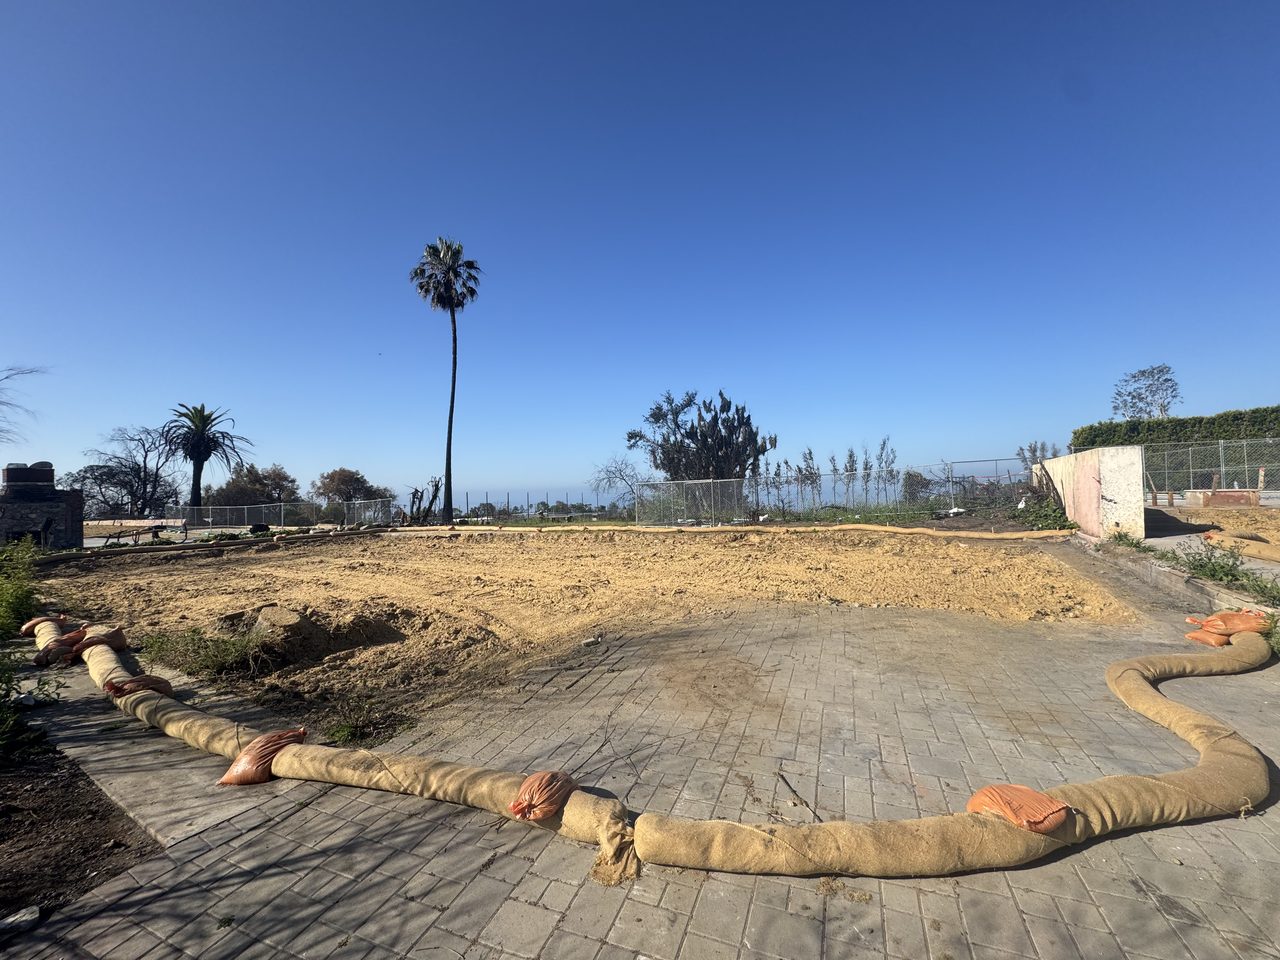
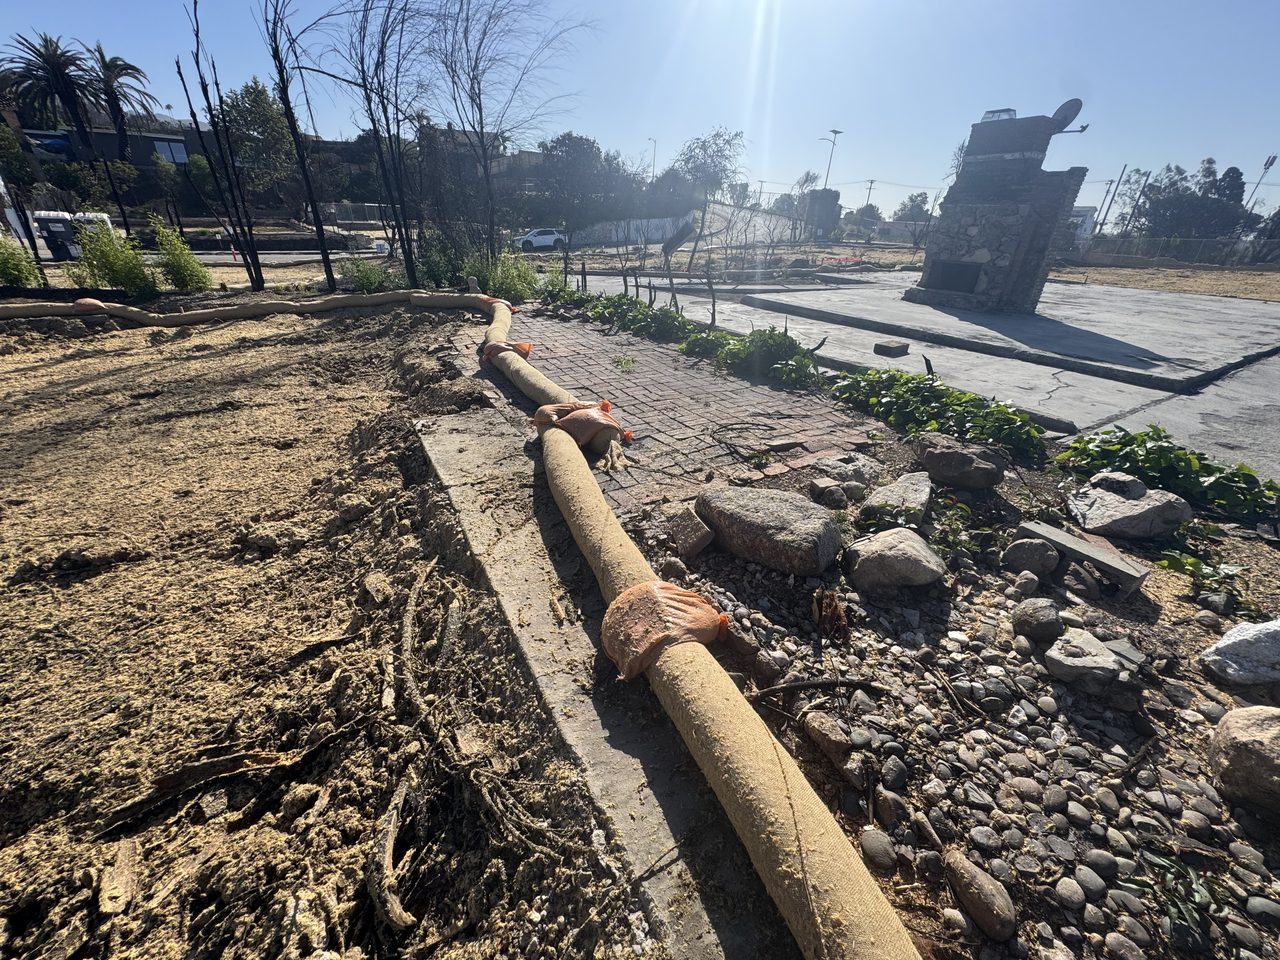
On January 9, 2025, a fast-moving wildfire swept through Pacific Palisades during a declared state of emergency and destroyed a 1961 single-family home. The stick-framed house burned to the ground, a total loss of the structure along with the garage and other improvements on a hillside lot.
The home was insured under a named-peril dwelling policy with replacement cost coverage and an ordinance or law endorsement for code-mandated upgrades. The owner hired Apex to handle the dwelling portion of the claim.
The Insurance Company's Response
The carrier opened its file treating the loss as a reported smoke damage claim and investigated under a full reservation of rights, raising a question as to whether the policy obligated it to provide coverage at all. Its early payment on the dwelling came to $750,000.
That figure did not reflect what it would actually cost to rebuild the home. It left out the demolition and removal of the fire-damaged foundation, driveway and concrete, the full framing and roof rebuild, the code upgrades that current California building standards require, and the cost of replacing the finishes the home actually had before the fire.
What the Insurer Got Wrong
The insurance company's initial assessment offered just $750,000, failing to account for the full scope of damage to the property.
What We Found
Apex inspected the site, brought in an independent estimating firm for a fire reconnaissance of the property, and had a licensed contractor prepare a line-item rebuild estimate at current local pricing. That scope documented what a true replacement required: demolition of the burned foundation and flatwork, new roof framing in dimensional lumber with sheathing, built-up roofing with drip edge, valley metal and flashings, boxed soffit and fascia reconstruction, insulation, and complete replacement of the plumbing, electrical and HVAC systems.
We also built the case for code-driven costs the first payment ignored. Rebuilding on this hillside lot requires grading, compaction and erosion control, and current California codes mandate fire-resistive construction under CBC Chapter 7A, Title 24 energy compliance including solar installation, and CALGreen requirements, all of which triggered the policy's ordinance or law coverage. Finally, we documented the home's pre-loss condition, including cherrywood paneling, natural stone cladding, slate flooring and a Roman tub, so the estimate replaced what was actually there rather than builder-grade substitutes.
In June 2025 we submitted a full proof of loss report covering structural damage, code compliance and the rebuild scope, supported by the contractor's estimate, a photo report, a jurisdiction-specific code checklist and a pre-loss condition assessment, and we pressed the carrier to respond to it.
The Result
Six months after Apex took over the claim, the carrier paid the dwelling coverage in full, exhausting the policy limit. The owner's dwelling recovery went from $750,000 to $1,520,000, an increase of $770,000, giving her the funds the policy actually provided for rebuilding the home.
Settlement Secured
We increased the settlement from $750,000 to $1,520,000, recovering an additional $770,000 — ensuring the property owner received full compensation for all damages.