Immediate Steps After a House Fire in San Jose
A house fire is one of the most devastating experiences a homeowner can face. In San Jose and Silicon Valley, where median home values exceed $1.4 million, the financial stakes are especially high. This guide walks you through exactly what to do after a fire to protect your family, your property, and your insurance claim.
If the fire has already happened and you need help with the claim now, see our San Jose fire damage claims page or our San Jose public adjusters page. The rest of this guide covers what to do, in order, and the San Jose specifics that change how a fire claim gets paid.
First 24 Hours: Safety and Documentation
1. Ensure Everyone's Safety
Your first priority is making sure all family members and pets are safe and accounted for. Do not re-enter the property until the San Jose Fire Department has cleared it as structurally safe.
2. Contact the San Jose Fire Department
If you haven't already, call 911. The fire department will document the incident and provide a fire report, which you'll need for your insurance claim. In San Jose, you can request a copy of the fire report from the SJFD Records Unit.
3. Document Everything
Once it's safe to approach your property:
- Take extensive photos and videos of all damage from multiple angles
- Document the exterior, interior, and all affected areas
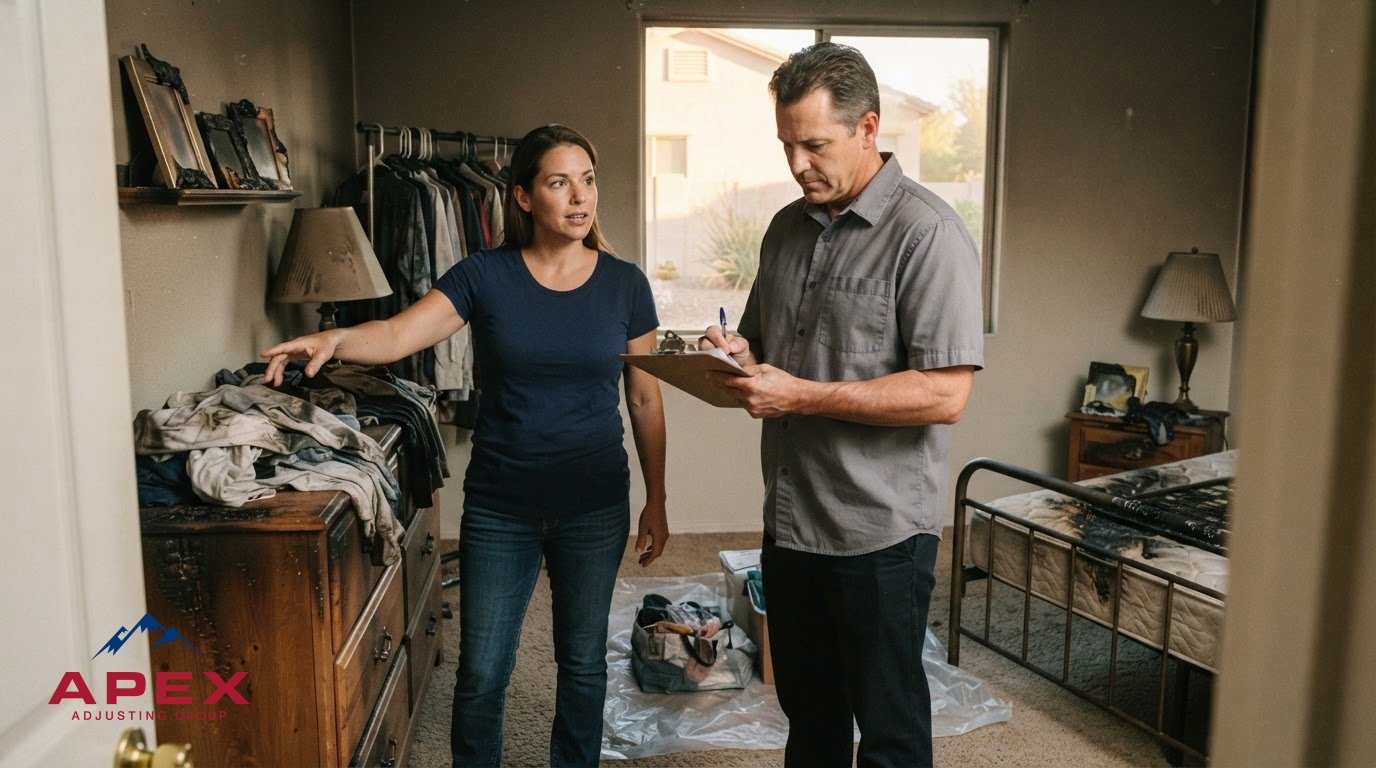
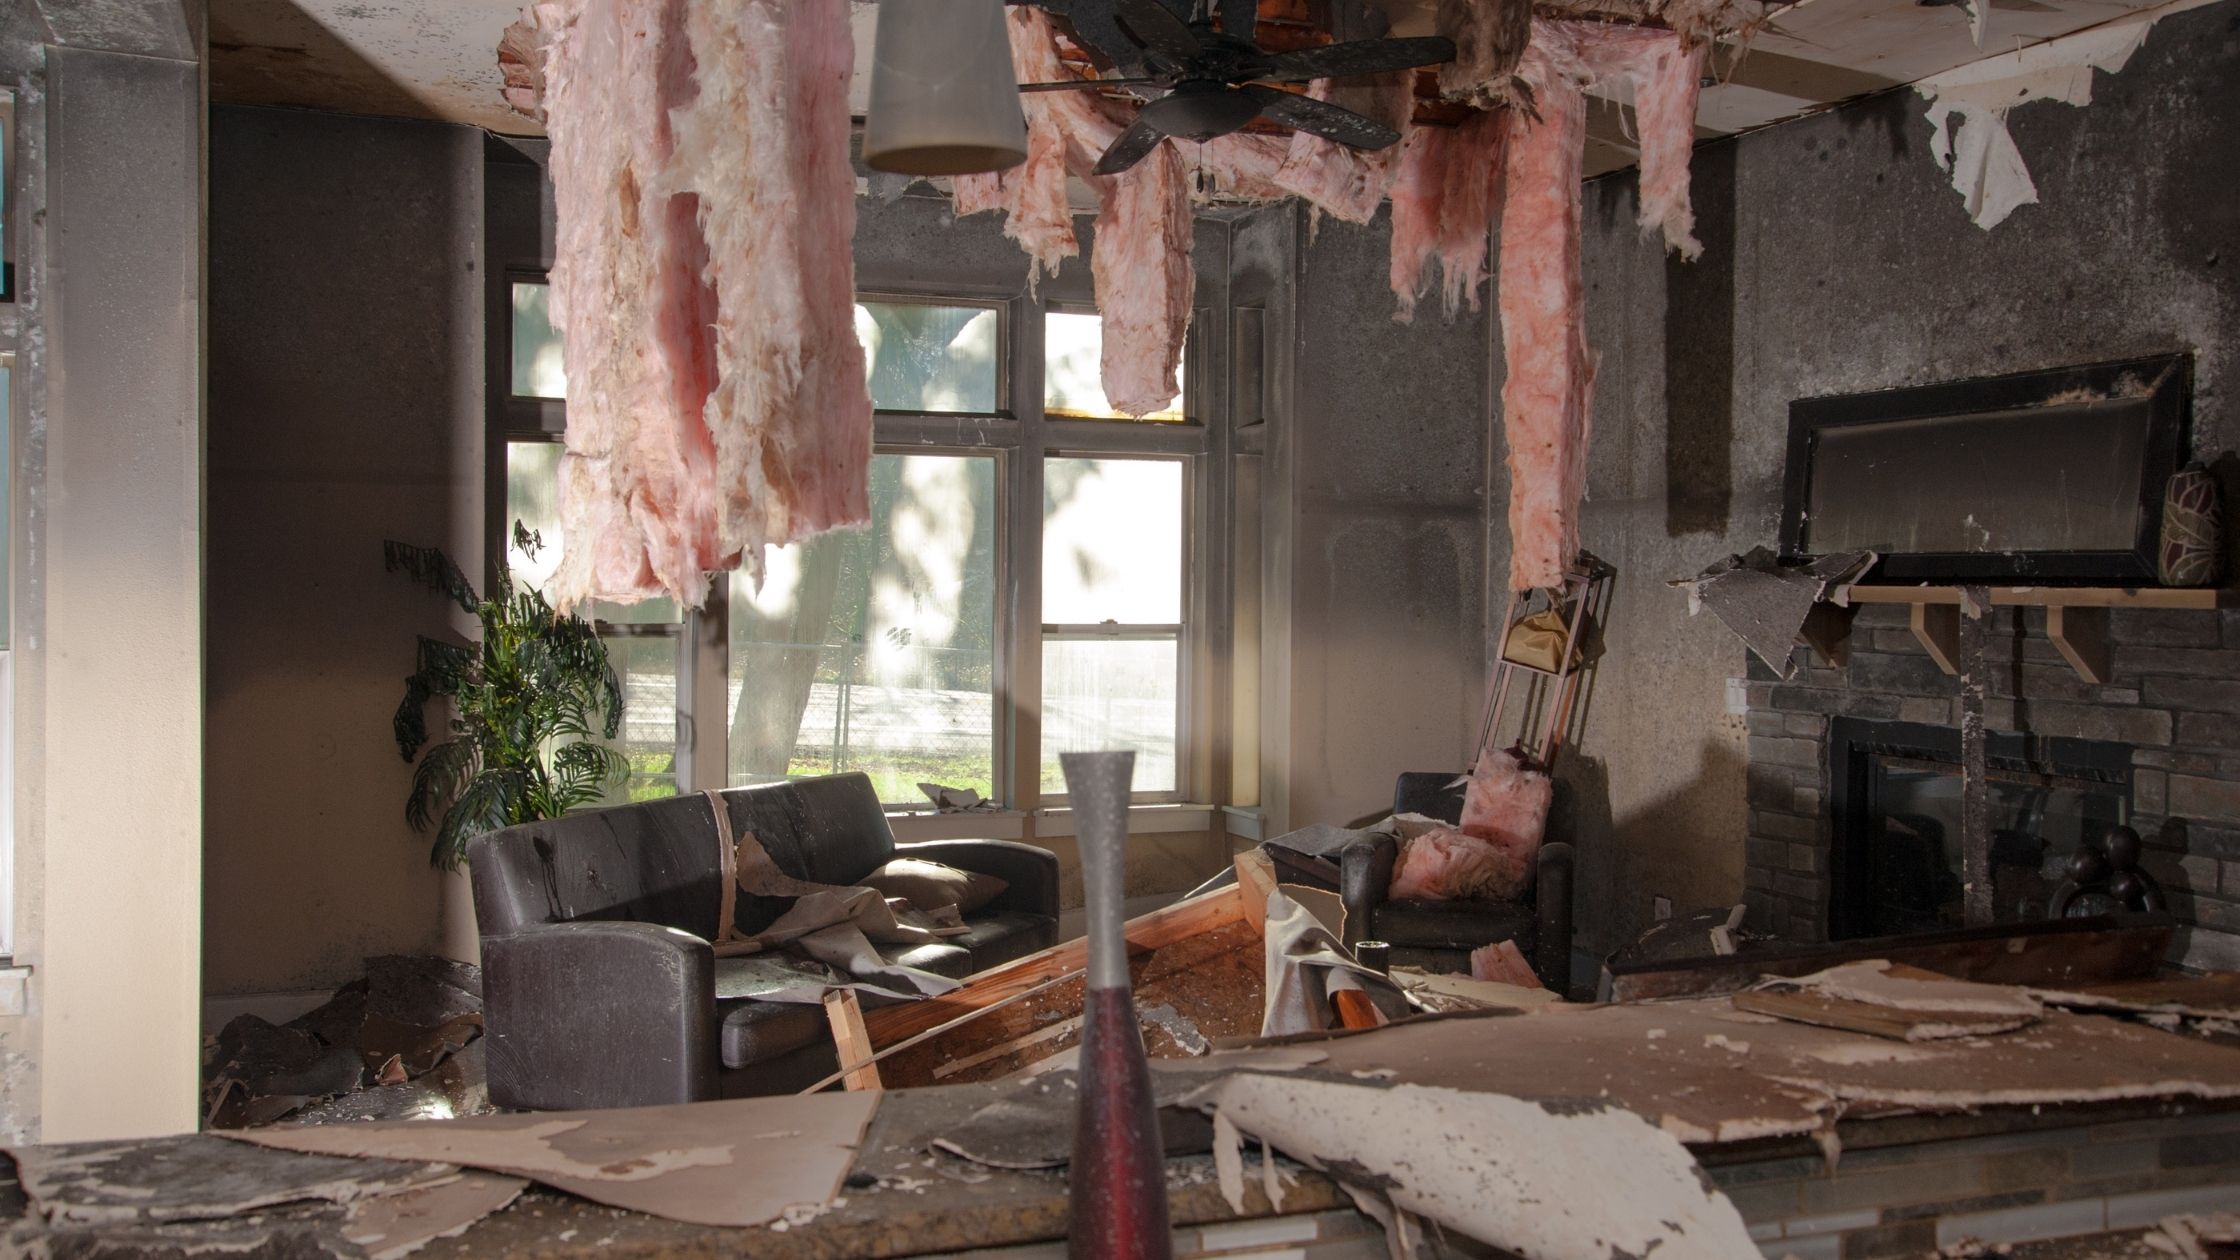
- Photograph smoke damage, water damage from firefighting, and structural damage
- Save all photos with timestamps
4. Notify Your Insurance Company
Contact your insurance company within 24 hours to report the loss. In California, insurers must acknowledge your claim within 15 days and begin investigation within 30 days.
Important: When speaking with your insurance company, provide basic facts about the fire but avoid making recorded statements or accepting blame without consulting a professional.
First Week: Securing Your Property and Claim
5. Secure the Property
Prevent further damage and protect against theft by:
- Boarding up windows and doors if necessary
- Covering roof damage with tarps
- Removing valuables if safe to do so
- Keeping all receipts for emergency repairs
6. Find Temporary Housing
Your homeowner's policy includes Additional Living Expenses (ALE) coverage for temporary housing. In San Jose, where average rents exceed $3,000/month, this coverage is critical. Keep all receipts for:
- Hotel stays
- Rental housing
- Meals above your normal expenses
- Storage costs
7. Create a Personal Property Inventory
Begin documenting all damaged or destroyed personal property. Include:
- Item description and age
- Estimated replacement cost
- Original purchase receipts if available
- Photos of items before the fire (from social media, emails, etc.)
Understanding Your Fire Insurance Claim in San Jose
What Does Fire Insurance Cover in California?
Standard California homeowner's insurance typically covers:
- Dwelling coverage: Structural damage to your home
- Personal property: Furniture, clothing, electronics, etc.
- Additional Living Expenses: Temporary housing and increased living costs
- Debris removal: Cost to clear damaged materials
- Code upgrades: Bringing rebuilt areas up to current San Jose building codes
Silicon Valley Reconstruction Costs
One of the biggest challenges in San Jose fire claims is reconstruction cost. While insurance companies often use statewide averages, actual Silicon Valley construction costs are significantly higher:
- Standard reconstruction: $550-$750 per square foot
- Custom finishes: $750-$1,000+ per square foot
- Code upgrades: $55,000-$150,000 additional
This is why many San Jose fire victims find their initial insurance offers fall significantly short of actual rebuilding costs.
San Jose Homes Bring Their Own Fire Claim Problems
Generic fire-claim advice assumes a generic house. San Jose's housing stock is anything but, and the type of home changes what the insurer will try to leave out.
Eichler homes
San Jose has several Eichler neighborhoods, including Fairglen, Rancho Santa Teresa and parts of Willow Glen. Their post-and-beam frames, tongue-and-groove ceilings, walls of glass and radiant heating in the slab do not repair like standard construction. Smoke and heat damage to an exposed wood ceiling usually means replacing the whole run to match, and a damaged radiant system can mean opening the slab. Carriers price these homes as if they were ordinary tract houses. The estimate has to reflect what the house actually is.
Older homes in Willow Glen, Naglee Park and the Rose Garden
Pre-war homes here often still have original knob-and-tube or early wiring, which is where many fires start. Rebuilding them triggers current electrical, energy and seismic code, and that cost belongs in the claim under Ordinance or Law coverage. It is routinely missing from the first estimate.
Downtown condos and townhomes
In a condo, two policies respond to the same fire: the HOA master policy covers the building and common areas, and your own HO-6 policy covers your unit's interior, contents and living expenses. Where one ends and the other begins depends on the HOA's governing documents, and the gaps between them are where owners lose money.
Hillside homes and wildfire smoke
Homes in the East Foothills, Evergreen, Almaden and Alum Rock sit next to grassland and brush that burn most summers, and the 2020 SCU Lightning Complex fires burned through the hills east of the city. Even when flames never reach the house, smoke and ash get into insulation, ductwork and contents. Smoke contamination is a covered loss, and it is one insurers often dismiss as a cleaning job.
California Deadlines That Protect You
California's Fair Claims Settlement Practices Regulations and Insurance Code set deadlines your insurer has to meet, and a few that protect you:
- 15 days: the insurer must acknowledge your claim and begin its investigation within 15 calendar days of notice (10 CCR 2695.5(e)).
- 40 days: once you submit proof of claim, the insurer has 40 days to accept or deny it, in whole or in part, and must explain any denial in writing (10 CCR 2695.7(b)).
- Time to rebuild: you have at least 12 months to collect the full replacement cost after the first payment of actual cash value, and at least 36 months after a loss in a declared state of emergency (Insurance Code 2051.5).
- Living expenses after a declared disaster: for a loss in a declared state of emergency, additional living expenses must be available for at least 24 months, with extensions for delays outside your control (Insurance Code 2060).
Keep a written log of every call, email and document request. If a deadline passes, that record is what makes it count.
A Real Santa Clara County Fire Claim
In a Cupertino fire loss we handled, the insurer's initial offer was $145,387. The claim settled at $742,687. The full write-up is in our case study, Cupertino Fire Damage Claim Increased From $145K to $742K.
Common Mistakes to Avoid
- Accepting the first offer: Insurance companies' initial offers often undervalue claims by 40-60%
- Throwing away damaged items: Keep everything until your claim is settled
- Not documenting thoroughly: More documentation means better claim outcomes
- Missing deadlines: California has specific timeframes for filing and supplementing claims
- Going it alone: Complex claims benefit from professional representation
When to Hire a Public Adjuster
Consider hiring a licensed public adjuster if:
- Your claim exceeds $50,000
- The insurance company disputes coverage or undervalues damage
- You're facing a total loss requiring reconstruction
- You don't have time to manage a complex claim
- The fire was caused by PG&E equipment (involving subrogation)
Public adjusters work on contingency - you pay nothing upfront, and fees come only from your settlement. Our San Jose clients typically receive settlements 3-5x higher than initial insurance offers.
San Jose Fire Damage Resources
- San Jose Fire Department: (408) 277-4444
- Red Cross Silicon Valley: (408) 292-6242
- California Department of Insurance: (800) 927-4357
- Apex Adjusting Group: (408) 669-3383
Get Expert Help With Your San Jose Fire Claim
Navigating a fire insurance claim in Silicon Valley's complex market requires expertise. At Apex Adjusting Group, we've recovered millions for San Jose homeowners facing fire damage. Our licensed public adjusters handle all aspects of your claim while you focus on recovery.
Call (408) 669-3383 for a free consultation. No recovery, no fee.
Need Help with Your Insurance Claim?
Our licensed public adjusters can help you get the maximum settlement you deserve. Contact us today for a free claim evaluation.
Related Articles